Use our GST calculator NZ guide to add, remove, or extract GST at 15%. Covers NZ registration thresholds, filing deadlines, accounting bases, and IRD compliance for 2024.

GST Calculator NZ: How to Add, Remove and Work Out Goods & Services Tax

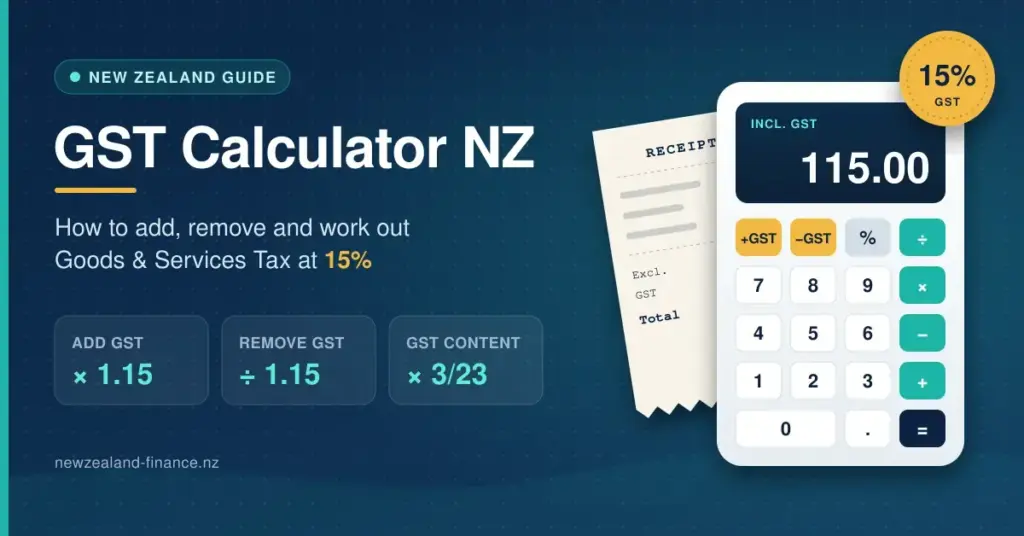

Whether you’re pricing a job, reconciling supplier invoices or simply checking what a receipt really cost, a dependable GST calculation is one of the most-used sums in New Zealand business. Goods and Services Tax touches almost every commercial transaction in the country, and small errors have a habit of compounding into real headaches with Inland Revenue (IRD). This guide walks through how GST works, every formula you’ll actually need, and the registration, filing and invoicing rules that sit around it — in plain language. It is general information, not tax advice.
What GST is
New Zealand introduced GST on 1 October 1986, and it has been a cornerstone of the tax system ever since. Unlike many countries that run multiple rates and large carve-outs, New Zealand’s GST is deliberately broad and flat — a design that keeps compliance costs low and makes the tax hard to avoid. It is a value-added tax collected at every stage of the supply chain, but only the final consumer bears the cost: a registered business charges GST on its sales (output tax), claims back the GST it paid on business purchases (input tax credits), and pays IRD the difference.
There are three categories to know. Standard-rated (15%) covers the vast majority of goods and services. Zero-rated (0%) covers exports, international transport and most land sales between GST-registered parties — these are still taxable supplies, so you can still claim input credits on related costs. Exempt supplies — residential rent, most financial services, and donated goods sold by non-profits — sit outside the GST net entirely, so no input credits can be claimed on costs that relate only to them. The rate has been 15% since 1 October 2010 (raised from 12.5%), with no credible signal of a change, so 15% is the working figure for all planning.
How to calculate GST: every formula
Four calculations cover almost everything you’ll ever do. The one to burn into memory is that you remove GST by dividing by 1.15, not by subtracting 15% — subtracting 15% gives the wrong answer every time.
- Add GST to a GST-exclusive price: multiply by 1.15. A $100 ex-GST price becomes $115.
- Find the GST on an exclusive price: multiply by 0.15. On $100, the GST is $15.
- Remove GST from a GST-inclusive price: divide by 1.15. A $115 inclusive price is $100 before GST.
- Extract the GST already inside an inclusive total (the 3/23 rule): multiply by 3 and divide by 23. On $115, that’s $115 × 3 ÷ 23 = $15.
The 3/23 rule works because GST of 15% sits inside an inclusive price as 15/115, which simplifies to 3/23. It’s the fastest way to split a till total into its net and GST parts when you only have the final figure.
GST calculations at a glance
| What you want to do | Formula | Worked example |
|---|---|---|
| Add GST to an exclusive price | price × 1.15 | $100 → $115 |
| Find the GST on an exclusive price | price × 0.15 | $100 → $15 |
| Remove GST from an inclusive price | price ÷ 1.15 | $115 → $100 |
| Extract GST from an inclusive total (3/23 rule) | total × 3 ÷ 23 | $115 → $15 |
Rule of thumb: never remove GST by subtracting 15% — always divide by 1.15, or use the 3/23 rule to pull the GST out of an inclusive total.
GST registration and the $60,000 threshold
You must register for GST once your taxable turnover exceeds — or is reasonably expected to exceed — $60,000 in any rolling 12-month period. That figure is gross revenue from taxable activity, not profit, and the threshold has stood at $60,000 since 2009. Once you are liable you have 21 days to register; miss that window and IRD can backdate your registration, leaving you owing GST on sales where you never collected it.
Below the threshold, registration is voluntary. It can still be worth it: registering lets you claim input tax credits on business purchases, which is especially valuable for start-ups and exporters with large up-front costs. The trade-off is more admin and having to add 15% to your prices, which can matter if your customers are the public rather than other GST-registered businesses. Registration itself is done online through myIR and is usually processed within a few working days — the official starting point is ird.govt.nz/gst, and business.govt.nz has a plain-English walk-through for small operators. GST sits alongside your other obligations, so it’s worth reading our New Zealand tax rates guide and income tax brackets explainer to see how it all fits together.
Accounting basis and filing frequency
When you register you choose an accounting basis, which decides when GST is counted:
- Payments (cash) basis: GST is counted when money actually changes hands. Your GST liability never runs ahead of your cash position, which is why it suits most small operators. Available up to $2 million turnover.
- Invoice basis: GST is counted when you issue or receive an invoice, regardless of payment. It can mean paying GST before a customer has paid you, but it lets you claim input credits sooner.
- Hybrid basis: a mix of the two, used only in specific situations.
You also choose a filing frequency. Two-monthly is the default. Six-monthly filing is available if your turnover is under $500,000, and monthly filing is compulsory above $24 million (and optional for refund-heavy businesses that want their credits back faster). Most returns are due on the 28th of the month after the period ends, with two fixed exceptions worth putting in your calendar now: a period ending 30 November is due 15 January, and one ending 31 March is due 7 May.
Invoicing: taxable supply information
This is the area most likely to trip up anyone working from older guidance, because the rules changed in 2023. Since 1 April 2023, the old “tax invoice” requirement was replaced by taxable supply information (TSI) — a more flexible framework. You can still head a document “Tax Invoice” if you like; what matters is that the required information is present and that you hold it. The low-value threshold also rose from $50 to $200 at the same time. The full detail is on IRD’s page covering ird.govt.nz — taxable supply information, and the tiers break down as follows.
Invoice requirements (taxable supply information)
| Supply value (incl. GST) | What you need to hold |
|---|---|
| Under $200 | Minimal records — enough to show a taxable supply occurred (supplier, date, description, amount). |
| $200 – $1,000 | Simplified TSI — supplier’s name and GST number, date, description, and the GST amount (or a statement that the price includes GST). No buyer details required. |
| Over $1,000 | Full TSI — the above plus the buyer’s name and address, with the GST amount shown as its own line. |
The low-value threshold rose from $50 to $200 in 2023. For supplies over $200 you must provide TSI to a GST-registered buyer within 28 days of a request.
For supplies over $200 you must provide TSI to a GST-registered buyer within 28 days of a request. Credit and debit notes are now called “supply correction information,” and because GST is quoted inclusively to consumers, your displayed retail prices must already include the tax — consumer.org.nz has useful background on GST-inclusive pricing and your rights as a shopper.
Common GST mistakes
Even experienced owners slip up. The classics are worth guarding against:
- Subtracting 15% instead of dividing by 1.15. A $115 inclusive price minus 15% gives $97.75, not the correct $100. Always divide by 1.15.
- Claiming GST on exempt or private expenses. You can’t claim on residential rent, personal costs, or the private-use portion of a mixed-use asset such as a part-personal vehicle.
- Missing the 21-day registration window after crossing $60,000, which exposes you to backdated liability.
- Treating zero-rated supplies as exempt. Exports are zero-rated, so you can still claim input credits on related costs — exempt supplies can’t.
- Not keeping records for seven years. IRD requires GST records to be retained that long.
Cloud accounting software (Xero, MYOB and similar) makes both the calculations and the record-keeping largely automatic, which removes most of these errors at the source.
GST and the bigger picture
GST doesn’t exist in isolation; for small business owners it interacts with income tax, provisional tax and employer obligations in ways that can create cash-flow pressure if they aren’t managed. A few principles help. GST isn’t your money — what you collect belongs to IRD, so keeping it in a separate account stops you spending it before the return falls due; our guides to small business loans and business finance cover managing the cash around tax time. Refunds are common for exporters and start-ups when input credits exceed output tax, usually paid within about 15 working days of an accurate return. And offshore digital services — streaming, software and online marketplaces supplied to New Zealand consumers — have had to charge New Zealand GST since 2016, so check whether an offshore supplier is registered before you try to claim the input credit for business use. If you also run payroll, the PAYE calculator guide covers the employee-tax side that sits beside your GST obligations.
Practical next steps
If you’ve read this far you’re well equipped to handle GST confidently. Bookmark the four formulas above; monitor your rolling 12-month turnover and start registering early if you’re approaching $60,000; choose your accounting basis to suit your cash-flow pattern (an accountant can advise); set calendar reminders for every filing date, including the non-standard 15 January and 7 May deadlines; and lean on cloud accounting software to automate the sums, generate compliant records and pre-populate your IRD returns. GST compliance isn’t glamorous, but get the foundations right — correct calculations, timely registration, accurate returns — and it becomes routine rather than a source of stress.
Disclaimer
This article is general information about GST in New Zealand, not tax advice, and it is not specific to your business. GST rules, thresholds and invoicing requirements change and carry exceptions — confirm the current position with Inland Revenue, or with a chartered accountant or registered tax agent, before relying on anything here for your own affairs. The authoritative source is IRD at ird.govt.nz/gst.
Sources
Frequently asked questions
What is the GST rate in New Zealand?
GST is 15%, and has been since 1 October 2010 (raised from 12.5%). It applies to the vast majority of goods and services; a few things are zero-rated, such as exports, or exempt, such as residential rent and most financial services.
How do I calculate GST?
To add GST to a GST-exclusive price, multiply by 1.15. To find the GST on an exclusive price, multiply by 0.15. To remove GST from a GST-inclusive price, divide by 1.15 (do not subtract 15%). To extract the GST already inside an inclusive total, multiply by 3 and divide by 23.
When do I have to register for GST?
You must register if your taxable turnover exceeds — or is expected to exceed — $60,000 in any rolling 12-month period (gross revenue, not profit). Once you are liable you have 21 days to register, or IRD can backdate it. Below the threshold you can register voluntarily to claim input tax credits.
Do I still need to issue a “tax invoice”?
Since 1 April 2023 the “tax invoice” requirement was replaced by “taxable supply information” (TSI), a more flexible framework. You can still label a document “Tax Invoice,” but what matters is that the required information is present: minimal for supplies under $200, simplified for $200–$1,000, and full (including buyer details) for over $1,000.
What are the GST filing deadlines?
Most businesses file two-monthly, due the 28th of the month after the period. Two exceptions apply: a period ending 30 November is due 15 January, and one ending 31 March is due 7 May. Six-monthly filing is available under $500,000 turnover, and monthly is required above $24 million (or voluntary for refund-heavy businesses).
No comments to show.
Best Brokers

Get approved fast with Finance Now. Personal loans, car finance & retail purchases – made easy for everyday Kiwis.

Shop now, pay later with Farmers Finance. Flexible payment options at Farmers stores across NZ – online and in-store.