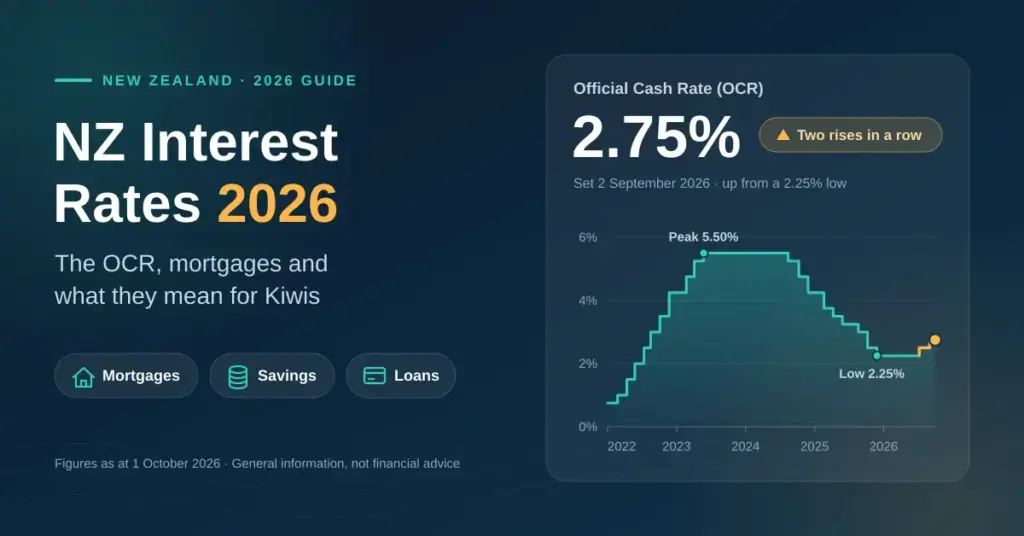
New Zealand’s interest-rate story has turned a corner. After the sharp hiking cycle of 2022-2023 and a long run of cuts through 2024 and 2025, the Reserve Bank has stopped cutting and started lifting the Official Cash Rate (OCR) again in 2026 — raising it twice in a row to 2.75%. This guide explains where rates sit, how the OCR flows through to what you pay and earn, and what the shift means for mortgages, savings and loans. It is general information, not financial advice, and because rates move constantly you should treat every figure here as a snapshot and check the current numbers before acting.
Key facts
| Measure | Where it sits (1 Oct 2026) |
|---|---|
| Current OCR | 2.75% (set 2 September 2026) |
| Previous move | 2.50% on 8 July 2026 — first rise since May 2023 |
| Recent low | 2.25% (reached late 2025, held in May 2026) |
| Current bias | Tightening — further rises more likely than cuts |
| Next OCR review | 28 October 2026 (markets lean to a hold) |
| Headline inflation | 4.1% (June 2026 quarter); ~2.9% excluding fuel |
| Reserve Bank mandate | Single price-stability target: 1–3%, 2% midpoint (since 20 Dec 2023) |
Where the OCR sits in late 2026
This is the key thing to understand about 2026: the story is no longer “rates are falling.” The OCR bottomed out at 2.25% in late 2025 and was held there in May 2026 on a split decision. Then, with inflation picking up again — largely on higher global oil prices — the Reserve Bank lifted the OCR to 2.50% on 8 July 2026 (its first increase since May 2023) and again to 2.75% on 2 September 2026. Both of those rises were unanimous. The environment has flipped from easing to a cautious tightening bias, and the Bank has signalled the next move is more likely up than down.
The next decision lands on 28 October 2026. At the time of writing, markets lean towards a hold at that meeting, with a further quarter-point rise to 3.00% seen as more likely at the 9 December review if inflation stays sticky. For the official decisions and the schedule of upcoming announcements, the Reserve Bank’s own page is the authoritative source (rbnz.govt.nz).
What the OCR is and why it matters
The Official Cash Rate is the Reserve Bank’s main lever for keeping inflation in check. It is the interest rate the Bank pays on money held overnight by commercial banks, and it anchors the rates those banks charge and pay everyone else. Raising it makes borrowing dearer and saving more rewarding, which cools the economy; cutting it does the reverse.
One point is widely misstated, so it is worth being precise. The Reserve Bank now operates a single mandate of price stability — keeping inflation between 1% and 3% over the medium term, with a 2% midpoint. The earlier “dual mandate” that also targeted maximum sustainable employment was removed when the current remit took effect on 20 December 2023; employment is now only something the Bank seeks to avoid adding unnecessary volatility to, not a goal in itself. (The change is politically contested — the main opposition party has said it would restore the dual mandate — but the rules in force in 2026 are inflation-only.) The Bank reviews the OCR about seven times a year, moving to eight reviews a year from 2027.
How an OCR change reaches you
A change in the OCR does not hit every product the same way or at the same speed. Understanding the plumbing helps you work out what a decision actually means for your own money.
- Floating (variable) mortgage rates move fastest. Banks usually pass an OCR change through to floating home-loan and overdraft rates within days or a few weeks, and almost one-for-one.
- Fixed mortgage rates often move first — but not because of the OCR directly. Fixed rates are priced off wholesale swap rates, which reflect where markets expect the OCR to head over the next one to five years. That is why fixed rates can rise or fall weeks before any official decision, and why your own fixed rate does not change at all until you refix.
- Savings and term deposit rates follow, with a lag. Banks tend to lift deposit rates a little more slowly than loan rates, so a rising OCR is good news for savers but you often have to shop around to capture it.
- Personal loans, car loans and credit cards barely flinch. These carry a large risk margin on top of the base rate, so an OCR move of 0.25% is usually lost in the noise.
The Financial Markets Authority has looked at how transparently banks pass OCR changes through to borrowers and savers — see its work at fma.govt.nz.
Where rates sit right now
Rather than a precise table that dates within weeks, here is the shape of the market as at late 2026, with the important caveat that the bias is now upward. The popular short fixed terms are still the cheapest way to borrow, but they have begun lifting as markets price in the tightening; floating rates sit well above the fixed options; and deposit rates are firming. For live, bank-by-bank numbers, interest.co.nz is the best source (interest.co.nz), and you can model your own repayments with our home loan calculator.
Rate snapshot
| Product | Typical level, late 2026 | Direction |
|---|---|---|
| Official Cash Rate (OCR) | 2.75% | Rising |
| Floating mortgage | Above 6% | Rising |
| 6-month fixed mortgage | ~4.75% | Edging up |
| 1-year fixed mortgage | ~4.95–5.20% | Rising |
| 2-year fixed mortgage | ~5.30–5.50% | Rising |
| 1-year term deposit | Up to ~4.15% | Firming |
| 2-year term deposit | Up to ~4.40% | Firming |
| Secured personal loan | ~10–15% | Little OCR effect |
| Unsecured / non-bank loan | Higher again | Little OCR effect |
| Credit card purchases | Above 20% | Mostly flat |
Indicative ranges only; rates vary by bank, term and your equity. Confirm live numbers on interest.co.nz or directly with lenders before acting.
A couple of things stand out. First, the one- and two-year fixed rates sit below floating, so most borrowers still fix. Second, the gap between what you can borrow at and what you can earn on a term deposit remains wide — a reminder that paying down debt is almost always a better “return” than saving at these levels.
What rising rates mean for you
A turning rate cycle affects different people in opposite directions. Here is how to think about it depending on where you sit.
If you have a mortgage
A rising-rate environment changes the calculus at refix time. When rates were falling, borrowers were rewarded for fixing short and rolling onto cheaper rates; when the bias turns up, a longer fix buys more certainty — but it also locks in a higher rate for longer, so there is no free lunch. The right call depends on your budget and how much certainty you want, and it is worth understanding how the main banks price their home loans before you commit. If your current deal is well above the market, refinancing to a sharper rate can be worth the paperwork — just check for break fees and cashback clawbacks first. And if higher repayments are genuinely stretching the budget, read up on the real cost of a mortgage holiday before using one, because capitalised interest makes it an expensive last resort.
If you are a saver
Firmer deposit rates are the silver lining of a tightening cycle. The difference between the best and worst term deposit rates is often half a percentage point or more, so it pays to compare rather than auto-rolling at maturity — our term deposit rates guide explains how to shop the market and the tax (RWT) that comes off your interest. Laddering several deposits across different maturities is a simple way to keep some money accessible while still locking in today’s higher rates.
If you are borrowing for something else
Personal, car and credit-card rates sit far above mortgage rates because of their risk margin, and they move little with the OCR — so the usual rules apply regardless of the cycle: compare the total cost, not just the headline rate. Our personal loans guide covers what to check and how the CCCFA protects you.
If you are in KiwiSaver or investing
Rate moves ripple into markets, but for long-term investors the lesson is usually to tune out the noise. Fund type and timeframe matter far more than any single OCR decision — see how to choose the right KiwiSaver fund for your stage of life rather than reacting to rate headlines.
Common mistakes to avoid
- Assuming fixed rates follow the OCR on the day. They are driven by swap rates and often move ahead of the Bank, so waiting for an official decision can mean missing the move.
- Auto-rolling a term deposit. The rollover rate is rarely the best on offer; a five-minute comparison can add real money.
- Fixing for the longest term purely out of fear. Certainty has a price — a longer fix at the top of a cycle can cost you if rates later fall.
- Treating a rate headline as advice. Your own situation — income stability, buffer, timeframe — matters more than where the OCR sits this week.
The outlook for 2027
The Reserve Bank’s job right now is to steer inflation back towards the 2% midpoint after headline inflation reached 4.1% in the June 2026 quarter (around 2.9% once volatile fuel prices are stripped out). Its own forecasts expect inflation to ease again over the following quarters, but with an upward bias on the OCR, the cutting cycle looks to be over for now. Markets are pricing a peak of roughly 3.00-3.30% by around mid-2027, though the Governor has stressed the Bank is “not on a preset course” and will move with the data. Because wholesale markets often shift months ahead of the Bank, fixed mortgage rates may well move before any official announcement — so the practical takeaway is to watch swap-rate commentary, not just OCR headlines, and to keep a repayment buffer in case the tightening runs further than expected.
Disclaimer
This article is general information about New Zealand interest rates, not financial advice, and not a recommendation about fixing, floating, borrowing or investing. Interest rates change frequently — the figures here are a snapshot as at 1 October 2026 and should be confirmed against current sources before you act. For the latest OCR and decision dates see the Reserve Bank (rbnz.govt.nz), and for current bank rates see interest.co.nz. For free, independent budgeting and money guidance, see sorted.org.nz (run by Te Ara Ahunga Ora Retirement Commission) or the MoneyTalks free helpline. If a large loan or a big decision is involved, consider advice from a licensed financial adviser or mortgage adviser about your own situation.
Sources
- Reserve Bank of New Zealand — Official Cash Rate decisions and schedule
- Reserve Bank of New Zealand — history of the remit and policy targets agreement
- interest.co.nz — current mortgage, savings and term deposit rates
- Opes Partners — current NZ mortgage interest rates tracker
- termdepositrates.co.nz — comparison of NZ term deposit rates
- Financial Markets Authority — OCR pass-through transparency
- Sorted (Te Ara Ahunga Ora Retirement Commission) — mortgages and saving
Frequently asked questions
What is the OCR right now?
As at 1 October 2026 the Official Cash Rate is 2.75%, following an increase on 2 September 2026 — the second rise in a row. It had earlier moved to 2.50% on 8 July 2026 from a low of 2.25%. The OCR is reviewed about seven times a year, so check rbnz.govt.nz for the latest; the next decision is due on 28 October 2026.
Are NZ interest rates still falling in 2026?
No — that has changed. After cutting through 2024 and 2025, the Reserve Bank started raising the OCR again in 2026 as inflation picked up, lifting it twice to 2.75%. It has signalled the next move is more likely up than down, so the cutting cycle appears to be over for now.
Should I fix or float my mortgage in 2026?
It depends on your situation. Floating gives flexibility but moves quickly with the OCR; fixing gives certainty but locks in today’s rate. In a rising-rate environment the trade-offs shift towards certainty, but a longer fix also means paying a higher rate for longer — so weigh how much certainty you want against your budget, and consider advice if a large loan is involved.
Does a 0.25% OCR change move my fixed mortgage rate straight away?
No. Fixed mortgage rates are driven mainly by wholesale swap rates, which reflect where markets expect the OCR to head — so fixed rates often move before a decision, and your own fixed rate does not change until you refix. Floating rates are the ones that move quickly after an OCR change.
Does the Reserve Bank still target employment?
No. Since the remit that took effect on 20 December 2023, the Reserve Bank has had a single price-stability mandate — keeping inflation between 1% and 3%, with a 2% midpoint. The earlier dual mandate that also targeted maximum sustainable employment was removed, though it remains a live political debate.