Everything you need to know about debt consolidation in NZ — how it works, whether a debt consolidation loan is right for you, what it costs, and how to apply.

Debt Consolidation in New Zealand: The Complete Guide

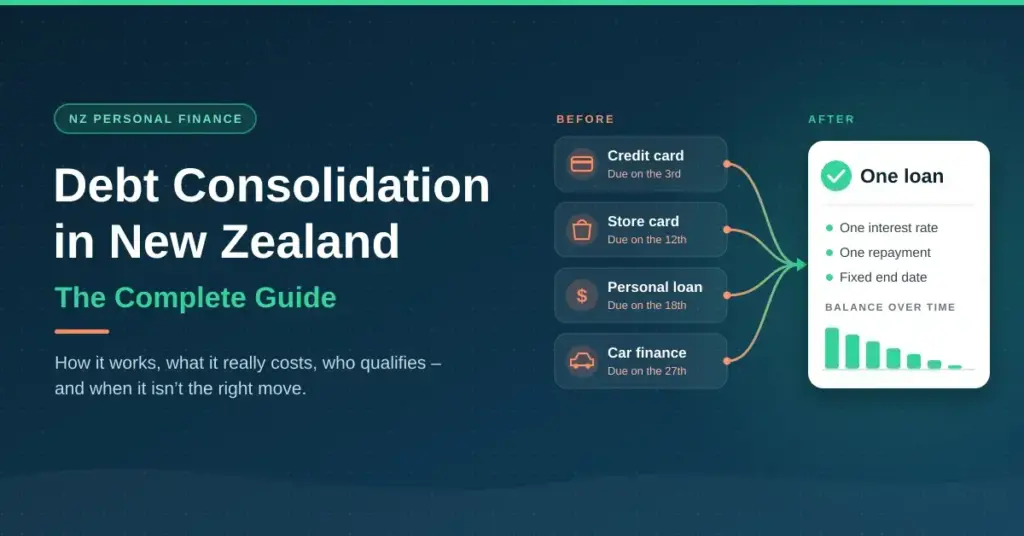

Debt consolidation rolls several debts — credit cards, store cards, personal loans, car finance — into a single loan with one interest rate and one repayment. The appeal is simple: instead of juggling four or five due dates and paying high credit-card interest, you replace the lot with one structured loan that has a fixed end date. With standard New Zealand credit-card purchase rates often sitting around 19–23% p.a., it has become one of the most-searched personal-finance topics in the country. This guide explains how consolidation works, what it really costs, who qualifies, and — just as importantly — when it is not the right move. It is general information, not financial advice.
What debt consolidation is and how it works
At its heart, consolidation is a swap: you borrow one new, larger sum, use it to clear your existing balances in full, and are then left with a single debt to repay. If the new loan carries a lower interest rate than the weighted average of the debts it replaces — and you keep the repayment term sensible — you pay less interest overall and reach a debt-free date you can actually see on the calendar. Just as useful for many people is the behavioural benefit: one automatic payment is far easier to manage than five, so you are less likely to miss one and trigger late fees or a credit-file black mark.
The important word is swap, not erase. The money you owe does not shrink the moment you consolidate; it simply changes shape. The arithmetic only works in your favour if the new rate and term genuinely cost less than carrying on as you are — and if you resist re-filling the cards you have just cleared. If you want a plain-English primer on borrowing first, our guide to how loans work in New Zealand is a good starting point.
Ways to consolidate in New Zealand
There is no single ‘consolidation loan’ product; it is a purpose you put an existing type of borrowing to. The three common routes are:
- An unsecured personal loan — from a bank, credit union or non-bank lender, typically over one to seven years. It keeps your debt separate from your home and has a clear end date, which is why it suits most people. Our personal loans guide covers how these are priced and compared.
- A mortgage top-up — homeowners borrow more against the house at a far lower rate. It is cheaper per dollar but carries real risks (covered below).
- A balance-transfer credit card — moving card balances onto a card with a low or 0% promotional rate. This can work well for card-only debt if you clear it inside the promo window, but the revert rate is high and new purchases often attract full interest immediately.
Key facts
- What it is: one new loan used to pay off several debts, leaving a single repayment and a fixed end date.
- Main routes: unsecured personal loan, mortgage top-up (homeowners), or a balance-transfer credit card.
- Typical personal-loan term: 1–7 years, usually at a fixed rate.
- Common fees: establishment fee ($0–$250), small monthly admin fee, possible PPSR and early-repayment fees.
- Rates are personalised: driven by your credit score, income and existing debts — not everyone gets the advertised rate.
- Best for: a fixed amount of higher-interest debt you can clear, when the new rate genuinely beats your current average and you can stop reloading the cards.
- Free help: MoneyTalks financial mentors on 0800 345 123 (or text 4029).
The true cost
Look beyond the headline rate. Unsecured personal-loan rates in New Zealand are personalised: lenders weigh your credit score, income, existing liabilities and employment stability, so borrowers with strong credit are offered the lower end of a lender’s range while those with impaired credit are quoted much higher rates — in which case consolidation may not actually save anything. Rates also move with the Official Cash Rate and lenders’ funding costs, so what is published today may differ from what you are personally offered.
On top of interest, factor in the fees: an establishment fee (commonly $0–$250), a small monthly or fortnightly admin fee ($2–$5 that adds up over a multi-year term), a PPSR registration fee if the loan is secured against a vehicle, possible early-repayment (break) fees on fixed-rate loans, and default fees if you fall behind. Most New Zealand consolidation loans are fixed-rate, giving predictable repayments; variable-rate loans exist too and often allow penalty-free extra repayments, which helps if you plan to pay down aggressively. Because the rate you are offered is driven by your credit file, it pays to check your credit score before you apply.
Who qualifies
Criteria vary between lenders, but most require you to be 18 or over; a New Zealand citizen, resident or valid visa holder; with stable, verifiable income; a credit history without recent defaults or insolvency; and enough income relative to your existing debts. Many digital lenders — including Harmoney, Lending Crowd and various credit unions — offer a soft-check quote, so you can see an indicative rate before a full application without affecting your score. Use this whenever you shop around.
If your credit is less than perfect and mainstream banks decline you or price the loan too high, a credit union (such as Unity or First Credit Union) often takes a more holistic view than a bank’s automated scoring. But be honest with yourself: if the only rate you can get is barely below what you already pay, free budget advice or a direct negotiation with your creditors may serve you better than new debt. Our bad credit loans guide walks through the realistic options and the red flags to avoid.
Mortgage top-up vs personal loan

For homeowners, a mortgage top-up can offer a rate well below any unsecured personal loan — but it carries risks worth thinking through carefully. First, you are converting unsecured debt into debt secured against your home, so falling behind now puts the house at risk, not just your credit score. Second, spreading consumer debt over a 25- or 30-year mortgage term dramatically increases the total interest paid — even at a lower rate, $15,000 of card debt stretched over two decades can cost far more than the same amount cleared on a three-year personal loan. Third, it can feel as though the debt has vanished when it has simply been absorbed into the mortgage, making it psychologically easier to run the cards back up.
If you do use a top-up, the trick is to structure the consolidated amount as a separate split with a short repayment term — matching the term you would have had on a personal loan — rather than rolling it into the main balance. That captures the lower rate without the decades of extra interest. Our guides to home loans in New Zealand and refinancing your mortgage can help you weigh the two approaches.
When it helps — and when it doesn’t
Consolidation tends to help when the new rate genuinely beats your current weighted-average rate, your income comfortably covers the single repayment, the debt is a fixed amount you can see yourself clearing, and you are ready to change the habits that built the debt in the first place. For someone paying 20%-plus on cards who can access a single-digit or low-teens personal-loan rate, the savings can be substantial and the simpler cash flow is a genuine relief.
It tends to backfire when the new rate is barely lower (or higher once fees are counted), when you stretch a small debt over a long term just to cut the monthly payment, or when the cleared cards get reloaded and you end up servicing both the consolidation loan and fresh card balances. If your real problem is that your outgoings exceed your income, a new loan treats the symptom, not the cause — and free budget advice will do more for you than more borrowing.
Applying, step by step
The process is streamlined these days. A sensible order of play:
- List every debt — balance, interest rate, minimum repayment and any break fees — so you know the weighted-average rate you are trying to beat.
- Check your free credit report (from Centrix, Equifax or illion) for errors, and fix any before applying.
- Get soft-check quotes from a few lenders and compare the total cost of the loan, not just the monthly repayment.
- Gather your documents — 90 days of payslips or bank statements, ID, and your current liabilities including credit-card limits, not just balances.
- Submit one formal application rather than several at once, since each hard enquiry can nudge your score down.
- Read the disclosure statement the CCCFA requires, checking the total amount repayable and every fee.
- Close or reduce the limits on the cleared cards once the old debts are paid — leaving them open with a zero balance is the temptation that derails many plans.
Alternatives and free help
A loan is rarely the only answer, and often not the best first step. A free, confidential financial mentor can look at your whole situation and suggest options you may not have considered — MoneyTalks runs a free helpline on 0800 345 123 (or text 4029), and its website at moneytalks.co.nz can connect you with a local mentor. Before you borrow, it is worth mapping your cash flow with a free budgeting tool such as the one at sorted.org.nz, and our own NZ budget planner guide explains how to build one. For serious, unmanageable debt, the formal solutions administered by the Insolvency and Trustee Service — a No Asset Procedure (for unsecured debts up to $50,000 with no realisable assets) or a Summary Instalment Order (for total debts of $50,000 or less where you can make instalments) — can offer a more complete reset than a new loan; see insolvency.govt.nz for the current rules.
A loan isn't the only option
- Balance-transfer credit card — a low or 0% promotional rate on transferred balances can work if you clear it within the window; revert rates are high.
- Negotiate with your creditors — lenders will often reduce rates or restructure repayments in genuine hardship. It costs nothing to ask.
- Free budget advice — a financial mentor can help you understand your cash flow before you borrow anything.
- Formal debt solutions — for serious, unmanageable debt, a No Asset Procedure or Summary Instalment Order (via the Insolvency and Trustee Service) can offer a more complete reset than a new loan.
- KiwiSaver hardship withdrawal — possible in significant hardship, but a genuine last resort given the long-term cost to your retirement.
- Free, confidential help — MoneyTalks: 0800 345 123. If debt feels overwhelming, a financial mentor can look at your whole situation at no cost — often a better first step than taking on new borrowing.
Your rights under the CCCFA

Lending in New Zealand is regulated under the Credit Contracts and Consumer Finance Act (CCCFA). Lenders must carry out responsible-lending checks (they cannot approve a loan they have reason to believe you cannot afford), give you a clear disclosure statement before you sign (showing the total repayable, all fees and the rate), and honour your right to apply for hardship relief if your circumstances change. Lenders must be on the Financial Service Providers Register, so always verify registration before proceeding. Since 1 July 2026 the Financial Markets Authority (FMA) regulates the CCCFA, taking over from the Commerce Commission, with lenders now operating under a market-services licence — but the core responsible-lending, affordability and disclosure protections remain in place. If a lender acts irresponsibly or unfairly, you can escalate to its dispute-resolution scheme (most belong to FSCL or the Banking Ombudsman) at no cost. For a plain-English rundown of your consumer rights, consumer.org.nz is a reliable source, and you can confirm a lender’s status via fma.govt.nz.
Your next steps
Debt consolidation is a tool, not a cure — the people who benefit most treat it as the start of a new chapter rather than just a way to cut this month’s payment. Before you apply, do the maths honestly: work out the total interest you will pay on your existing debts if nothing changes, then compare it with the total cost of a consolidation loan at the rate you are realistically likely to be offered (not the best advertised rate). If the numbers stack up and you are confident you can resist reloading the cleared cards, consolidation can be a genuinely powerful step. Start by pulling your free credit report, mapping your cash flow with a budgeting tool, and getting soft-check quotes from two or three lenders — and if anything feels unclear, talk to a free budget adviser before you sign anything.
Disclaimer
This article is general information about debt consolidation in New Zealand. It is not financial advice and not a recommendation of any lender or product. Rates, fees and eligibility are personalised and change over time — always compare the total cost of borrowing at the rate you are actually offered, and read the disclosure statement before signing. If debt feels unmanageable, free, confidential help is available from MoneyTalks on 0800 345 123 (moneytalks.co.nz) — often a better first step than taking on new borrowing.
Sources
- Financial Markets Authority — changes to credit laws and the CCCFA transfer: fma.govt.nz
- Insolvency and Trustee Service — No Asset Procedures and Summary Instalment Orders: insolvency.govt.nz
- Consumer Protection (MBIE) — borrowing money, bankruptcy and insolvency: consumerprotection.govt.nz
- Sorted — free budgeting tool and adviser directory: sorted.org.nz
- MoneyTalks — free financial mentoring (0800 345 123, or text 4029): moneytalks.co.nz
- Consumer NZ — your rights under the CCCFA: consumer.org.nz
Frequently asked questions
What is debt consolidation and how does it work in New Zealand?
It means taking out a single new loan to pay off several existing debts — credit cards, store cards, personal loans and the like. In New Zealand you can consolidate through an unsecured personal loan (from a bank, credit union or non-bank lender) or a mortgage top-up if you own a home. The goal is a lower overall interest rate, one repayment to manage, and a clear date by which you will be debt-free.
Will a debt consolidation loan hurt my credit score?
Applying triggers a hard enquiry, which can cause a small, temporary dip. Over time, though, if consolidation helps you make consistent on-time payments and lowers your credit utilisation, it can improve your score. Use soft-check quotes while you are shopping around so your score is not affected until you are ready to apply formally.
What interest rate can I expect?
Rates are personalised based on your credit, income and existing liabilities — strong profiles get the lowest rates, while impaired credit means higher rates or no offer from mainstream lenders. Always check current rates directly, because they move with the Official Cash Rate and market conditions. The real test is whether your consolidated rate beats the weighted-average rate across the debts it replaces.
Is it better to consolidate into my mortgage or take a personal loan?
A mortgage top-up usually has a lower rate, but it converts unsecured debt into debt secured against your home, and spreading it over a long term can cost far more in total interest despite the lower rate. If you use a top-up, structure it as a separate split with a short term. For most people without equity — or who want to keep their home separate from consumer debt — an unsecured personal loan is the cleaner option.
What should I do if I can’t qualify?
If lenders decline you, or the rate does not make consolidation worthwhile, speak to a free budget adviser, contact your creditors directly to negotiate reduced rates or a hardship arrangement, or try a credit union. For serious, unmanageable debt, formal options such as a Summary Instalment Order or a No Asset Procedure through the Insolvency and Trustee Service may fit better than more borrowing.
No comments to show.
Best Brokers

Get approved fast with Finance Now. Personal loans, car finance & retail purchases – made easy for everyday Kiwis.

Shop now, pay later with Farmers Finance. Flexible payment options at Farmers stores across NZ – online and in-store.