Everything Kiwis need to know about interest free credit cards in NZ — how Gem Visa works, the real costs, the credit card interest free period trap, and smarter alternatives.

Interest-Free Credit Card NZ: How Gem Visa Works and How to Use It Wisely

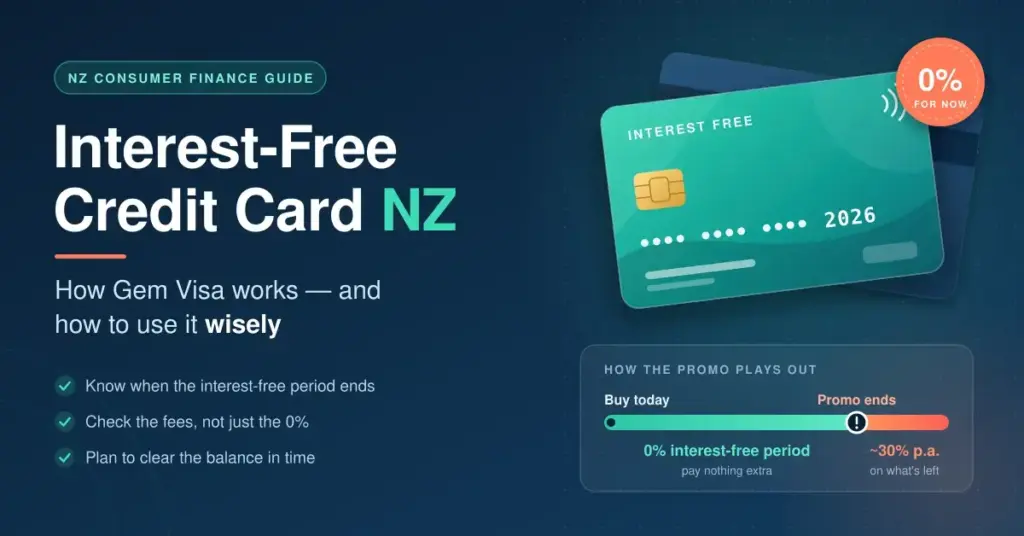
An interest-free credit card can look like free money: walk into a store, carry home a new heat pump, laptop or lounge suite today, and pay nothing extra for a year or two. In New Zealand the best-known version of this deal is the Gem Visa, and in the right hands it genuinely can save you money. But “interest free” is a conditional offer, not a gift — and thousands of Kiwis each year discover the catch only when the promotional period quietly ends and a rate close to 30% lands on whatever balance is left. This guide explains who runs Gem Visa, what it really costs in 2026, exactly how the interest-free period works, your rights under New Zealand law, and the cheaper ways to pay for a big purchase. It is general information, not financial advice.
What Gem Visa is and who’s behind it
Gem Visa — and the related Gem CreditLine account — is issued by Latitude Financial Services Limited, an Australian consumer-finance company that trades in New Zealand as Gem Finance. Latitude partners with hundreds of New Zealand retailers to offer promotional interest-free finance at the checkout. Those “18 months interest free” or “24 months interest free” signs on televisions, appliances and furniture are almost always a Gem (or a competing Q Card / Q Mastercard) deal.
Away from those promotions, Gem Visa behaves like an ordinary Visa card: it runs on the Visa network, so you can tap or swipe it anywhere Visa is accepted, here or overseas. The difference is the price. Outside a promotion the card charges one of the highest ongoing interest rates on the New Zealand market, so using it for everyday spending without an active interest-free offer is rarely a good idea. You can see current retail rates alongside other providers in our guide to comparing credit cards in New Zealand.
Common participating categories include electronics and appliances (for example Noel Leeming, Harvey Norman and PB Tech), furniture and bedding (such as Freedom and Forty Winks), and optical retailers like Specsavers. The retailer list and the length of each offer change regularly, so always confirm the current partners, offer terms and rates at gemfinance.co.nz before you shop.
It helps to understand the business model. The retailer effectively pays Latitude to offer the finance, because an interest-free deal closes more sales and encourages larger baskets. That is not sinister in itself — it can be a genuinely good deal if you repay on time — but it does mean the card is designed to be easy to open at the point of sale, often in a few minutes, when you are focused on the product rather than the contract. Treating the application with the same care you would give a loan, rather than an afterthought at the till, is the single biggest thing that separates people who benefit from Gem Visa from those who are caught out by it.
The real costs in 2026
The interest-free headline is only one part of the picture. Gem Visa also carries fixed fees and a very high “revert” interest rate, and the fees were increased in 2026. Here is what you are actually signing up for.
- Purchase interest rate: 29.49% p.a. This applies to any balance left after a promotional term ends, and to any non-promotional spending. For context, most standard New Zealand credit cards sit somewhere around 13–22% p.a.
- Cash advance rate: 29.95% p.a., plus a $2 fee per cash advance. Cash advances usually attract interest from day one, with no interest-free days — avoid them.
- Annual account fee: $65, billed as $32.50 every six months (up from $55 previously).
- Establishment fee: $55, a one-off charge when the account is opened.
- International transaction fee: around 2% on purchases made in a foreign currency or processed overseas.
- Minimum monthly repayment: 3% of the outstanding balance or $20, whichever is greater.
There is also a standard offer separate from the big in-store promotions: new general purchases of $250 or more can get 0% interest for six months when you opt in within 30 days. That is useful, but it does not remove the annual and establishment fees — so for a single modest purchase those fixed costs can easily outweigh the interest you save.
Gem Visa at a glance
| Issuer | Latitude Financial Services Limited |
| Trades in NZ as | Gem Finance |
| Card network | Visa — accepted anywhere Visa is accepted |
| Standard interest-free offer | 0% for 6 months on purchases of $250+ (opt in within 30 days) |
| In-store promotions | 0% interest offers from 6 to 60 months at participating retailers |
| Purchase interest rate | 29.49% p.a. (applies after any promotion ends) |
| Cash advance rate | 29.95% p.a. plus a $2 fee per advance |
| Annual account fee | $65, billed as $32.50 every six months |
| Establishment fee | $55 one-off |
| International transaction fee | around 2% on foreign-currency spending |
| Minimum monthly repayment | 3% of the balance or $20, whichever is greater |
| Regulator | Financial Markets Authority (CCCFA, from 1 July 2026) |
| Official page | gemfinance.co.nz |
Figures as at 2026. Rates, fees and offers change — confirm current details on gemfinance.co.nz before you apply.
How the interest-free period actually works
This is the part most people skip in the excitement of a big purchase, and it is the single most important thing to understand. The interest-free term is a promotional arrangement tied to a specific purchase, not a permanent feature of the card.
The revert-rate trap
“Interest free” means you pay no interest only if you clear the whole promotional balance before the term ends. The interest does not build up quietly in the background and then get waived if you finish on time. Instead, any balance still owing on the day the term ends immediately starts accruing at the full 29.49% p.a. rate. You must also keep making the minimum monthly payment throughout the term, or you can lose the interest-free benefit early.
Here is why that matters. Say you buy a $3,000 appliance on 24 months interest free and only ever pay the 3% minimum. You will chip away at it slowly, but the minimum is designed to keep you in debt, not to clear the purchase on schedule — so a large chunk is still owing when month 24 arrives. From that moment the leftover balance compounds at nearly 30% a year, which can add hundreds of dollars. Before you commit, it is worth modelling the required monthly payment with a tool such as our loan calculator guide so you know the figure that actually clears the balance in time.
Running more than one promotion at once
Many shoppers open a Gem account for one purchase and then use it again, ending up with two or three promotions running at the same time, each with a different end date. Keeping track of which payment is reducing which balance becomes genuinely difficult. Latitude applies your repayments according to its own allocation rules set out in the contract — not necessarily to the balance expiring soonest — so read your monthly statement carefully and, if in doubt, make extra payments well ahead of the earliest deadline.
Applying for Gem Visa, and your rights
You can apply online at gemfinance.co.nz or in store at a participating retailer. You will generally need photo ID, proof of income, your IRD number and details of your existing debts and regular expenses. Latitude must carry out a responsible-lending assessment under the Credit Contracts and Consumer Finance Act (CCCFA), the law that governs all New Zealand consumer credit — including buy-now-pay-later, which was brought under the CCCFA in 2024. If your application is declined, you can review your credit score and file — for example through a credit bureau such as Centrix (centrix.co.nz) — to understand what lenders are seeing.
Under the CCCFA, Latitude must give you a clear disclosure statement before you sign — including the rate that applies once any promotion ends — lend responsibly, and allow you to request a hardship variation if your circumstances change. A hardship application is a formal right: if illness, job loss or another unexpected event means you cannot meet the repayments, you can ask the lender to vary the contract — for example by extending the term or reducing payments for a period — and the lender must consider it. Importantly, regulatory oversight of the CCCFA transferred from the Commerce Commission to the Financial Markets Authority (FMA) on 1 July 2026 (fma.govt.nz). The change is administrative — your protections as a borrower are unchanged — but it does mean the FMA, rather than the Commerce Commission, is now the body overseeing responsible-lending conduct. If you believe Latitude has fallen short, raise it with the company first, then escalate to its external dispute-resolution scheme, which is free to use. For independent reviews of credit products, Consumer NZ (consumer.org.nz) is a useful starting point.
Cheaper ways to fund a big purchase
Gem Visa is not the only way to pay for a large item, and it is often not the cheapest. The right choice depends on the size of the purchase, how long you need to repay it, and how confident you are of clearing it on time.
- A bank or finance-company personal loan. If you genuinely cannot clear a promotional balance within the term, a fixed-rate personal loan is almost always cheaper than leaving money on a Gem card at 29.49%. You get a fixed term and a fixed repayment, with no revert-rate surprise.
- A standard low-rate credit card. For purchases you can pay off within a billing cycle or two, an everyday card at roughly 13–22% p.a. (or a balance that never carries over) can work out cheaper once Gem’s fees are counted.
- Consolidating existing balances. If a Gem balance has already reverted and is sitting at the high rate, a debt consolidation loan may cut the interest while you clear it.
- Buy now, pay later. Services like Afterpay or Zip suit smaller amounts and charge no interest if you pay on schedule, though late fees apply.
- Lay-by, or simply saving ahead. If you can wait, setting the money aside first — for instance in a term deposit — avoids debt, fees and revert-rate risk entirely.
A quick way to sanity-check any of these is to add up the total you will pay, not just the headline rate. For Gem Visa that means the purchase price, plus the $55 establishment fee, plus the $65 annual fee for every year the account stays open, plus any interest if you miss the deadline. On a planned $4,000 purchase cleared inside a 24-month promotion, the fixed fees alone are around $185 — small against the purchase, but worth weighing if the interest-free window is short or the amount is modest. Run the same total-cost sum for a personal loan or a low-rate card and the cheapest option is usually obvious.
How the costs compare
| Option | Typical cost in 2026 | Best suited to |
|---|---|---|
| Gem Visa interest-free promo | 0% during the term, then 29.49% p.a. on any balance left; $65/yr account fee + $55 establishment fee | A planned large purchase you are confident of clearing before the term ends |
| Standard low-rate credit card | Roughly 13–22% p.a.; often an annual fee | Smaller purchases paid off within a cycle or two |
| Bank / finance-company personal loan | Fixed term, roughly 7–20% p.a. depending on your credit | Larger amounts repaid over one to five years |
| Buy now, pay later (e.g. Afterpay, Zip) | $0 interest if paid on schedule; late fees apply | Small, short-term purchases |
| Lay-by or saving up first | No interest, no fees, no debt | Anything you are able to wait for |
Indicative only; rates vary by lender and by your circumstances. Compare current offers before deciding.
Using Gem Visa wisely: a checklist
If a Gem Visa interest-free deal really is the right tool for a specific, planned purchase, these steps keep it working in your favour rather than against you:
- Work out the repayment that actually clears the balance in time — the purchase price divided by the number of promotional months, plus a small buffer — not the lender’s minimum.
- Set up an automatic payment the day you open the account, so repayment never depends on memory. Build the amount into your household budget from the start.
- Put a calendar reminder two months before the promotion ends to check you are on track and top up if needed.
- Never use the card for everyday spending, and avoid cash advances entirely.
- Once the purchase is paid off, consider closing the account if you will not use it again, to stop the annual fee — noting that closing a credit line can have a minor, short-term effect on your credit score.
The bottom line
Gem Visa can genuinely help in the right hands: a large, necessary purchase, a clear repayment plan, an automatic payment set up on day one, and real confidence you will clear the balance before the promotion ends. Used that way, the interest-free period is exactly what it says. But if you tend to make only minimum repayments, already juggle several credit products, or are not certain you can clear the balance in time, the 29.49% revert rate makes it one of the most expensive ways to borrow in New Zealand. In that situation a personal loan, a low-rate card, or simply saving up first will almost always cost less. The smartest move before any big purchase is to compare the full cost of every option — fees included — rather than signing up for whatever the checkout terminal happens to be offering.
A note on responsible borrowing
This section is factual information, not encouragement to take on debt. Interest-free finance only stays interest free if the balance is cleared on time; otherwise the cost can be substantial. Borrow only what you can comfortably repay, read the disclosure statement in full before you sign, and keep a note of every promotional end date. If repayments are becoming a struggle, free and confidential budgeting help is available from MoneyTalks on 0800 345 123 (moneytalks.co.nz), and Sorted, run by Te Ara Ahunga Ora Retirement Commission, has independent guidance on debt and borrowing (sorted.org.nz).
Sources
- Gem by Latitude — Gem Visa card rates and fees
- Financial Markets Authority — the CCCFA
- Commerce Commission — transfer of consumer-credit regulation to the FMA
- Canstar NZ — Gem credit cards overview
- Consumer NZ — credit card reviews and guidance
- Sorted — debt and borrowing guides
- MoneyTalks — free financial mentoring (0800 345 123)
- Centrix — check your credit score and file
Frequently asked questions
What is the Gem Visa interest rate in New Zealand?
The standard purchase rate is 29.49% p.a. in 2026. It applies to any balance left after a promotional interest-free term ends, and to any non-promotional spending. That is well above most standard New Zealand cards, which sit around 13–22% p.a. Cash advances cost even more — 29.95% p.a. plus a $2 fee — and should be avoided. Rates can change, so confirm the current figure at gemfinance.co.nz.
How does the interest-free period actually work?
It is a promotional deal tied to a specific purchase at a participating retailer, not a permanent card feature. You must make the minimum monthly repayment throughout the term. If you clear the full promotional balance before the term ends, you pay no interest on it; if any balance remains, it immediately begins accruing interest at 29.49% p.a. from that date.
What fees does Gem Visa charge?
There is a $65 annual account fee, billed as $32.50 every six months, plus a one-off $55 establishment fee when you open the account. Foreign-currency transactions attract a fee of around 2%. These fixed costs matter especially if you are opening the card for a single purchase, because they can outweigh the interest the promotion saves you.
What happens if I only make the minimum repayments?
The minimum — typically 3% of the balance or $20, whichever is greater — is not designed to clear a large purchase within the promotional term. A big chunk will still be owing when the term ends, and that remaining balance then attracts the 29.49% rate, potentially adding hundreds or thousands of dollars. To stay interest free, pay the purchase price divided by the number of promotional months, not the minimum.
What are cheaper alternatives for a large purchase?
If you cannot be sure of clearing a promotional balance in time, a fixed-rate bank personal loan is usually cheaper than the 29.49% revert rate. A standard low-rate card suits purchases you can repay within a cycle or two, buy-now-pay-later suits smaller amounts, and lay-by or saving up first avoids debt and fees altogether. Compare the total cost, including fees, before deciding.
No comments to show.
Best Brokers

Get approved fast with Finance Now. Personal loans, car finance & retail purchases – made easy for everyday Kiwis.

Shop now, pay later with Farmers Finance. Flexible payment options at Farmers stores across NZ – online and in-store.