Understand income tax NZ — how NZ tax brackets work, how your tax is calculated step by step, what PAYE means, and how to make sure you’re paying the right amount.

Income Tax NZ: Complete Guide to NZ Tax Brackets and How It’s Calculated

Income tax touches almost every dollar a working New Zealander earns — a weekly wage, a contractor’s invoice, bank interest, dividends, or rent from an investment property. Yet plenty of people couldn’t say which bracket they sit in, how much of their pay actually reaches Inland Revenue (IRD), or why a pay rise sometimes feels smaller than expected. This guide sets out the current New Zealand tax brackets, shows step by step how the figures are worked out, and explains the levies and repayments that come out alongside income tax so there are no surprises at year end. It is general information, not personal tax advice.
How income tax works, and the current brackets
New Zealand runs a progressive income tax system. That simply means your income is divided into bands, and each band is taxed at its own rate — a higher rate only ever applies to the slice of income that falls inside the higher band, never to your whole income. The rates apply to your taxable income: broadly, your gross income minus any allowable deductions. For most employees that is simply their salary or wages; for the self-employed it is business income after expenses.
Most income is taxable — salary and wages, self-employment and contracting income, rental income, bank interest, and dividends (which usually arrive with imputation credits attached). If you are a New Zealand tax resident, overseas income is generally taxable here too. A few things are not taxed: the sale of your family home in most cases, and genuine gifts or inheritances. One important exception for property investors is the bright-line test, which currently taxes the gain on a residential investment property sold within two years of buying it (the two-year rule has applied since 1 July 2024). For a broader overview of every tax type in the country, see our New Zealand tax rates guide, and you can always confirm the current personal rates on Inland Revenue’s tax rates for individuals page.
NZ income tax brackets
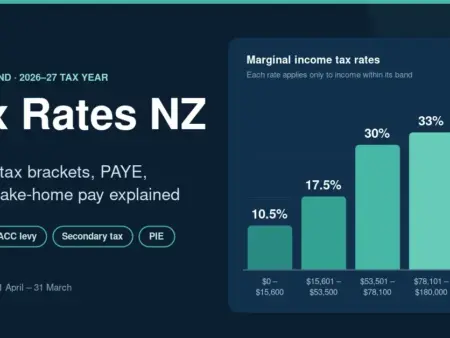
These are the rates for the 2026–27 tax year. The thresholds were last raised on 31 July 2024 and are unchanged from 2025–26. Rates are marginal, so each applies only to the slice of income inside its band.
| Taxable income | Tax rate |
|---|---|
| $0 – $15,600 | 10.5% |
| $15,601 – $53,500 | 17.5% |
| $53,501 – $78,100 | 30% |
| $78,101 – $180,000 | 33% |
| $180,001+ | 39% |
Worked example: on $60,000 you pay 10.5% on the first $15,600, 17.5% on the next $37,900 and 30% on the final $6,500 — about $10,220 in total, an effective rate of roughly 17%. There is no tax-free threshold, so tax applies from the first dollar.
How your tax is calculated: worked examples
The quickest way to see the system in action is to run the numbers. Say you earn $60,000 a year. You do not pay 30% on the whole amount, even though $60,000 reaches into the 30% band. Instead you pay 10.5% on the first $15,600, 17.5% on the next $37,900 (the slice from $15,601 to $53,500), and 30% only on the final $6,500. That adds up to about $10,220 of income tax for the year — an effective rate of roughly 17%, well under the 30% top marginal rate that applies to your last dollar.
The same logic scales up. On $85,000 you would pay 10.5%, 17.5% and 30% on the lower slices exactly as above, then 33% only on the $6,900 that sits above $78,100 — about $17,930 in total, or an effective rate near 21%. Because the lower bands are always taxed at the lower rates first, your effective (average) rate is always lower than your marginal (top) rate. There is no tax-free threshold in New Zealand, so tax applies from the very first dollar you earn.
PAYE and getting your tax code right
If you are an employee, you almost certainly pay through PAYE — Pay As You Earn. Your employer calculates and deducts your income tax, the ACC earners’ levy and any student loan repayments every payday, then passes them to Inland Revenue on your behalf, so most salary and wage earners never have to file a return. What does matter is your tax code: it tells your employer how much to withhold, and the wrong one is the single most common reason people end up with an unexpected bill or an overpayment. Common codes include M (your main or highest-earning job), M SL (main job with a student loan), ME (main job where you qualify for the Independent Earner Tax Credit), and secondary codes such as S, SH or ST for a second job. Since 2019, Inland Revenue has issued an automatic end-of-year assessment — usually between May and July — using information it already holds from employers and banks, so most people simply receive a refund or a small bill without lifting a finger. To see how a salary translates into take-home pay, try our PAYE calculator guide.
Deductions that come out alongside income tax
Income tax is rarely the only thing leaving your pay. For most employees, PAYE bundles several other deductions together, and a couple of the figures changed in 2026, so they are worth checking.
What PAYE takes out of your pay
- Income tax — deducted each payday from the brackets above, based on your tax code. The wrong code is the top cause of a surprise bill or refund.
- ACC earners’ levy — a flat levy funding injury cover, currently about 1.75% of earnings up to an annual cap. On a $65,000 salary that is roughly $1,138 a year. It is separate from income tax but still reduces take-home pay.
- KiwiSaver — your contribution (the default is 3.5% from 1 April 2026, or you can choose 4%, 6%, 8% or 10%) comes out of your pay, and your employer adds at least 3.5% on top. Contribute at least $1,042.86 across the year and the government tops you up by up to $260.72.
- Student loan — if you have one, 12% of every dollar you earn above $24,128 a year is deducted automatically. New Zealand loans stay interest-free while you live here.
- Secondary tax — a second job uses a secondary code (S, SH, ST…) with higher withholding. It is not an extra tax; it just prevents underpayment, and Inland Revenue squares up your total at year end.
The ACC earners’ levy funds cover for injuries that happen away from work; the current rate is about 1.75% of your earnings up to an annual cap, and you can read how it is set on acc.co.nz. If you qualify for the Independent Earner Tax Credit — worth up to $520 a year for earners between $24,000 and $70,000 who don’t receive Working for Families or a main benefit — you claim it simply by using the ME code, and the full rules are on Inland Revenue’s IETC page. KiwiSaver contributions also come out here; our KiwiSaver guide explains how the scheme works, and if you want to sense-check your fund and Prescribed Investor Rate, see our guide to choosing a KiwiSaver provider and fund.
Self-employed, contractors and business owners
Provisional tax
If you work for yourself, PAYE doesn’t apply to your business income. Instead you pay provisional tax — effectively pre-paying the year’s expected tax in instalments (usually three) rather than in one lump sum. You generally enter the provisional tax system once your residual income tax (the tax left owing after any credits) is expected to exceed $5,000 in a year. There are several ways to calculate it: the standard method (105% of last year’s residual income tax), the estimation method (your own forecast), and the accounting income method, or AIM, which calculates tax as you go through approved accounting software. Underpaying can trigger use-of-money interest, so a common rule of thumb is to set aside around 25–30% of what you earn for tax.
GST
GST (goods and services tax) is separate from income tax. You must register once your turnover passes $60,000 in any 12-month period; the rate is 15%, which you add to your prices, collect from customers, and pass on to Inland Revenue through regular GST returns. Registering voluntarily below the threshold can make sense if you have significant business expenses to claim back. Our GST guide walks through registration, returns and how it is calculated.
Tax on investment income
Investment income is taxed according to its type. Interest from a bank account is taxed at your marginal rate through Resident Withholding Tax (RWT) — you nominate the correct rate when you open the account, and getting it wrong leaves a gap to square up later. Money held in a PIE (portfolio investment entity), which includes KiwiSaver and many managed funds, is taxed inside the fund at your Prescribed Investor Rate (PIR), capped at 28%. For higher earners that cap can be lower than their marginal rate, so setting the right PIR genuinely saves money; set it too low and you’ll owe the difference. Dividends from New Zealand companies usually carry imputation credits for tax the company has already paid, while shares in overseas companies may fall under the Foreign Investment Fund (FIF) rules. If your income has changed recently, it is worth reviewing both your PIR and your RWT rate.
Common mistakes to avoid
A handful of errors account for most tax-time surprises:
- Using the wrong tax code — especially easy when you start a new job or take on a second one.
- Not declaring all income — rental, freelance, Airbnb and overseas earnings are all taxable, and Inland Revenue receives data from banks and overseas tax authorities.
- Setting an incorrect PIR — too low means a bill, and unlike other overpayments a PIR set too high has historically not been refunded, so accuracy matters.
- Missing provisional tax instalments — which can lead to use-of-money interest.
- Forgetting the bright-line test before selling a residential investment property inside the two-year window.
Your next steps
The fundamentals are manageable once you can see the structure behind them. Log in to myIR and check that your tax code, PIR and any year-end assessment look right; review your KiwiSaver PIR if your income has changed; and if you are self-employed, open a separate account and set money aside for tax and GST as you go. If your affairs are more complex — a rental property, overseas income or a growing business — a registered tax agent usually pays for themselves. For plain-language help with budgeting and money decisions, sorted.org.nz is a trustworthy free resource, and it is worth knowing roughly where your pay sits against the average salary in New Zealand. Finally, bookmark Inland Revenue’s rates page and glance at it each April, when thresholds and levy rates can change.
A quick note on terminology: if you have come across “income tax slabs”, Section 87A rebates or rupee thresholds, those belong to India’s tax system and have no bearing on your New Zealand tax. For anything concerning tax in New Zealand, Inland Revenue is the authority.
Disclaimer
This article is general information about income tax in New Zealand and is not tax or financial advice. Tax rates, thresholds, levy rates and credits are set by law and change over time — the figures here reflect the 2026–27 tax year. Always confirm the current figures and your own obligations with Inland Revenue or a registered tax agent before you act, and reach out to a free service such as Sorted or MoneyTalks if money worries are affecting you.
Sources
Frequently asked questions (FAQ)
What are the current income tax rates in New Zealand?
For the 2026–27 tax year (unchanged from 2025–26), the five progressive brackets are: 10.5% on income up to $15,600; 17.5% on $15,601–$53,500; 30% on $53,501–$78,100; 33% on $78,101–$180,000; and 39% on income over $180,000. You only pay each rate on the portion of income that falls within that band. These thresholds were last raised on 31 July 2024, so older figures such as $14,000/$48,000/$70,000 are out of date.
Is there a tax-free threshold in New Zealand?
No. Tax applies from the very first dollar you earn, starting at 10.5% on income up to $15,600. There is no personal allowance like the one some countries offer, although the Independent Earner Tax Credit gives a small credit to eligible earners on between $24,000 and $70,000.
What is the difference between my marginal and effective tax rate?
Your marginal rate is the rate charged on your last dollar of income — for example 30% if you earn between $53,501 and $78,100. Your effective rate is the average across all your income, which is always lower because the lower bands are taxed first. Someone earning $75,000 has a 30% marginal rate but an effective rate of roughly 19.6%.
Do I need to file a tax return?
Most salary and wage earners do not — Inland Revenue issues an automatic end-of-year assessment using data from employers and banks. However, if you have self-employment, rental, overseas or other untaxed income above $200 in a year, you will need to file an IR3 individual return through myIR.
How does provisional tax work?
If your residual income tax is expected to exceed $5,000, you pay provisional tax in instalments (usually three a year). The common standard method bases each payment on 105% of last year’s residual income tax. Missing instalments can trigger use-of-money interest, so it helps to set reminders and put money aside as you earn.
No comments to show.
Best Brokers

Get approved fast with Finance Now. Personal loans, car finance & retail purchases – made easy for everyday Kiwis.

Shop now, pay later with Farmers Finance. Flexible payment options at Farmers stores across NZ – online and in-store.