Compare the best travel insurance NZ options for 2024 â from AA Travel Insurance to Southern Cross, Tower and beyond. Understand cover types, costs, pre-existing conditions and how ACC fits in.

Travel Insurance NZ: The Complete Comparison Guide

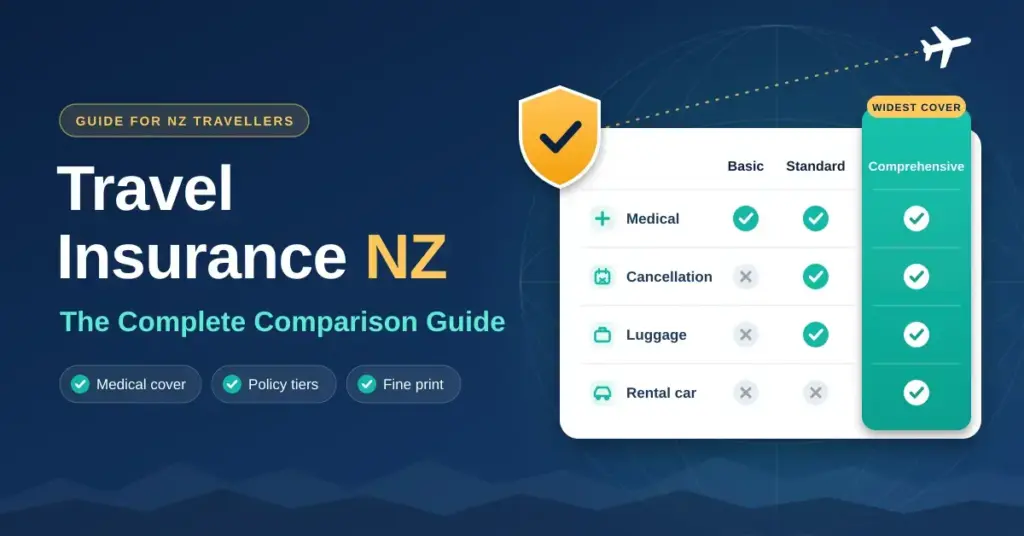
Choosing travel insurance can feel like navigating a maze — dozens of providers, confusing policy tiers and fine print only a lawyer could love. Yet getting it wrong can cost far more than the premium you saved: a single medical evacuation from the United States or Europe can run to NZ$80,000–$150,000 before hospital bills, specialist fees and the expense of a family member flying over to be with you. This guide cuts through the noise so you can compare like with like, understand what actually matters, and leave New Zealand with genuine peace of mind. It is general information, not financial advice.
Key points
- ACC stops at the border. New Zealand’s accident scheme pays nothing towards overseas medical treatment — travel insurance is the only thing standing between you and a foreign hospital bill.
- Unlimited medical cover is the benefit that matters most. A fixed cap can fall short in the United States; unlimited overseas medical and repatriation removes the biggest financial risk.
- Compare wording, not just price. Excess, activity exclusions and pre-existing-condition terms differ far more than the headline premium.
- Declare pre-existing conditions honestly. Non-disclosure, even accidental, can void the whole policy.
- Buy as soon as you book. Cancellation cover starts from purchase, protecting non-refundable deposits straight away.
- Free help exists if a claim is declined — the Insurance & Financial Services Ombudsman (IFSO) reviews disputes at no cost.
The New Zealand market — and the ACC gap
New Zealand’s travel insurance market is competitive and well regulated. Insurers must be licensed and sit under Financial Markets Authority conduct oversight, so you have meaningful protections, including free access to an independent dispute-resolution scheme if a claim goes wrong. But one feature makes the Kiwi market unlike almost anywhere else, and it catches travellers out every year.
At home, the Accident Compensation Corporation (acc.co.nz) covers the cost of treating accidental injuries on a no-fault basis. That cover does not follow you across the border. The moment your flight leaves New Zealand airspace, ACC stops paying for accident-related medical treatment, and you are entirely reliant on travel insurance for anything that happens overseas. ACC may help with follow-up treatment back in New Zealand if you were away for less than six months, but it will not touch the overseas hospital bill itself.
Before you commit to a destination it is also worth checking the government’s SafeTravel service (safetravel.govt.nz), run by the Ministry of Foreign Affairs and Trade. Many insurers reduce or void cover for travel to a country, or a region within it, that carries a government “Do not travel” advisory, so the advisory level can directly affect whether you are insured.
What actually matters when you compare
The phrase “best travel insurance” means different things to different travellers — a 25-year-old backpacking through Southeast Asia has very different needs from a 65-year-old couple on a European river cruise. Price is the easiest number to compare and the least useful on its own. Instead, read the Policy Wording (sometimes called the Product Disclosure Statement) and weigh these areas against each other.
When you request quotes, make sure you are comparing like with like: enter the same destinations, exact travel dates, the same traveller ages and the same level of baggage and cancellation cover across every provider. A policy that looks NZ$30 cheaper often carries a higher excess, a lower medical cap or an activity exclusion that only surfaces at claim time. Set the benefits first, then let price break the tie — not the other way round.
Overseas medical and evacuation cover
This is the single most important benefit, because it is the one that can bankrupt you. Look for unlimited overseas medical and repatriation cover rather than a fixed cap. Some budget policies limit medical to NZ$1–2 million, which sounds generous but can fall short of a long intensive-care stay in a US hospital. Check that emergency medical evacuation and “bringing you home” (repatriation) are included, and that a travelling companion can be funded to stay with you.
Cancellation and disruption
Cancellation cover reimburses non-refundable deposits — flights, tours, accommodation — if you have to cancel for a covered reason such as illness, injury or a family bereavement. Limits range from a few thousand dollars on basic plans to NZ$50,000 or more on premium ones; pick a limit that reflects what you have actually prepaid. Some insurers sell a “cancel for any reason” add-on that refunds a partial amount with no specified cause, at a higher premium.
Baggage, theft and delays
Baggage cover pays towards lost, stolen or damaged luggage, usually with a per-item limit (so high-value items like cameras or laptops may need to be specified). Travel-delay and missed-connection benefits pay a set amount for meals and accommodation when transport fails. These are modest sums, but they are also the benefits people claim on most often.
Activities, exclusions and the excess
Adventure activities — skiing, scuba diving, bungy, quad bikes, mountaineering — are frequently excluded unless you add optional cover. If your trip involves anything active, confirm it is named in the policy. Every policy also has an excess (the amount you pay per claim); a lower premium often simply hides a higher excess, so compare the two together. Finally, read the general exclusions: alcohol- and drug-related incidents, unattended belongings and undeclared pre-existing conditions are the classic reasons a claim is declined.
The main providers compared
Several insurers dominate the New Zealand travel market, and their strengths differ. The table below sets out the best-known options and what distinguishes each; it is a factual summary, not a ranking, and benefits change, so always confirm the current wording on the insurer’s own site. Independent reviews from consumer.org.nz are a useful second opinion.
Comparison
| Provider | Background | Overseas medical cover | Stands out for | Official site |
|---|---|---|---|---|
| Southern Cross Travel Insurance | 100% NZ-owned, operating 40+ years | Unlimited on Comprehensive and Medical Only plans | Established NZ specialist; pre-existing conditions assessed over a 36-month window | scti.co.nz |
| AA Travel Insurance | Backed by Allianz emergency assistance | Unlimited overseas medical | Tiered international plans and an AA-member discount | aa.co.nz |
| Tower | Long-established NZ general insurer | From about NZ$250k on entry plans up to unlimited on higher tiers | Familiar NZ brand with tiered cover | tower.co.nz |
| Cover-More | Underwritten by Zurich New Zealand | High to unlimited, depending on plan | Basic, Comprehensive and Comprehensive+ tiers; trans-Tasman scale | covermore.co.nz |
| 1Cover | Australian-backed, online-focused | High medical limits, strong luggage cover | Competitive online pricing; some pre-existing conditions included as standard | 1cover.co.nz |
| World Nomads | International, adventure-travel focus | Capped but high overseas medical | Wide list of covered adventure activities for backpackers | worldnomads.com |
AA Insurance is one brand many Kiwis recognise — its travel policies come in tiered plans, AA members can receive a premium discount, and cover is backed by Allianz 24/7 emergency assistance; see our AA Insurance guide for background. Tower also offers tiered travel cover, and our Tower Insurance review covers the company in more depth. Whichever you consider, compare the policy wording — especially the adventure-activity and pre-existing-condition terms — rather than just the brand or the headline price. If the choice feels overwhelming, our guide to insurance brokers explains how an adviser can match a policy to your trip.
Single-trip versus annual multi-trip
If you travel more than twice a year, an annual multi-trip policy is almost always better value than buying single-trip cover each time. One annual premium covers every journey within the year, up to a maximum trip duration — commonly 30, 45 or 60 days. The maths is straightforward: a single comprehensive policy for a two-week trip might cost NZ$120–$250, while an annual multi-trip policy typically runs NZ$300–$800 depending on your age, destinations and the per-trip cap. Take three or more trips and you are usually ahead. The catch to watch is the maximum trip duration clause: for a longer journey — say six weeks in Europe — check the per-trip limit stretches that far, or buy a dedicated single-trip policy for that leg.
Don’t overlook domestic cover
Many Kiwis assume they need no travel insurance within New Zealand because ACC covers accidents. But ACC will not cover non-accident illness (food poisoning, appendicitis), trip cancellation and non-refundable bookings, rental-vehicle excess, or lost or stolen baggage. If you have booked a domestic holiday with non-refundable flights and accommodation, a domestic travel policy can protect those costs when illness or a family emergency forces you to cancel — and it is often surprisingly affordable, sometimes under NZ$50 for a short trip.
Older travellers and pre-existing conditions
Premiums rise significantly with age, particularly above 70, and some providers apply upper age limits or require a medical assessment for travellers over 75 or 80. If you have a pre-existing condition — anything from asthma to a past heart event — the process usually runs: complete an online medical assessment when you buy; the insurer then covers the condition (sometimes for an extra premium), excludes it, or declines cover; and you receive written confirmation of what is covered. The look-back window varies by insurer, from 12 months to five years or more, and the assessment usually asks about hospital admissions, surgery, medication changes and any condition under investigation. Never assume a condition is covered because you didn’t mention it: full disclosure is a cornerstone of the insurance contract, and non-disclosure — even unintentional — can lead to a claim, or the whole policy, being declined. Pregnancy is treated as its own category by most insurers, often covered up to a set number of weeks, so check that term carefully if it applies. If you are weighing ongoing health costs more broadly, our guide to health insurance in New Zealand is a useful companion.
Extended trips, your Big OE and tax
If you are planning a Big OE or an extended working holiday, two things change. First, standard annual policies cap each trip, so a months-long absence usually needs a dedicated long-stay or backpacker policy. Second, your New Zealand tax-residency status may shift: Inland Revenue (ird.govt.nz) treats you as a non-resident only if you are away for more than 325 days in any 12-month period and you no longer have a permanent place of abode here — both tests must be met. That status can affect your KiwiSaver contributions and how any New Zealand income is taxed, so it is worth getting advice before a long trip.
How to claim — and what to do if you’re declined
A smooth claim starts before anything goes wrong. Keep every receipt — medical bills, pharmacy dockets, repair quotes — because claims without documentation are routinely reduced or declined. Report theft or loss to the local police within 24–48 hours and get a written report; without one, a baggage claim will usually fail. For any significant medical treatment, call the insurer’s 24/7 emergency assistance line before you are treated where possible: pre-authorisation protects you and speeds reimbursement. Lodge the claim promptly on your return, typically within 30–60 days.
If a claim is declined and you believe that is wrong, use the insurer’s internal complaints process first. If you are still unhappy, you can escalate — free of charge — to the Insurance & Financial Services Ombudsman (ifso.nz), an independent scheme that reviews disputes and can make awards that are binding on the insurer.
Before you book: a short checklist
The best time to buy travel insurance is immediately after you book your trip, not at the airport, because cancellation cover then starts straight away and protects your deposits from day one. Run through this before you pay:
- Decide your cover type — comprehensive, essential or medical-only.
- Check whether you need adventure-sports or specific-activity cover.
- Declare every pre-existing condition honestly and get the answer in writing.
- Compare at least three providers on their wording, not just price.
- Read the exclusions and the excess before you buy.
- Save your policy number and the 24/7 emergency line in your phone.
- Check the SafeTravel advisory for every destination on your route.
Travel insurance isn’t glamorous, but it is one of the smartest financial decisions you can make before any trip: the premium is a known, modest cost, while the alternative — an uninsured medical emergency abroad — is not.
Disclaimer
This article is general information about travel insurance in New Zealand. It is not financial advice and not a recommendation of any insurer or policy. Cover, limits, exclusions and premiums vary by policy and by traveller, and change over time, so always read the full Policy Wording (Product Disclosure Statement) and compare a few providers before you buy, and declare any pre-existing conditions honestly. For independent reviews see Consumer NZ (consumer.org.nz); for destination advisories see SafeTravel (safetravel.govt.nz); and if a claim dispute cannot be resolved with your insurer, contact the Insurance & Financial Services Ombudsman.
Sources
- SafeTravel (MFAT) — destination advisories and official travel-insurance guidance: safetravel.govt.nz
- ACC — what is and isn’t covered, including injuries overseas: acc.co.nz
- Consumer NZ — travel insurance reviews and your rights when a claim is declined: consumer.org.nz
- Insurance & Financial Services Ombudsman (IFSO) — free dispute resolution: ifso.nz
- Inland Revenue — tax residency and the 325-day rule for extended travel: ird.govt.nz
Frequently asked questions
Do I need travel insurance if ACC covers accidents?
Yes. ACC covers accidental injury inside New Zealand only — it does not follow you overseas, so abroad you are entirely reliant on travel insurance for accident-related medical costs. Even at home, ACC does not cover non-accident illness, trip cancellation, rental-vehicle excess or lost baggage, so travel insurance still has a role on a domestic holiday.
How much medical cover do I actually need?
Look for unlimited overseas medical cover on any comprehensive policy. Some budget plans cap medical at NZ$1–2 million, which can fall short in a US hospital, and a repatriation with a medical escort from North America or Europe alone can run to NZ$80,000–$150,000. Unlimited cover removes that risk entirely.
What happens with pre-existing medical conditions?
Most policies exclude them unless you declare them and, often, pay an additional premium. The definition of “pre-existing” varies by insurer, with look-back windows from 12 months to five years or more. Declare any ongoing condition honestly and get written confirmation of cover, because failing to disclose can void the entire policy, not just the medical claim.
Is annual multi-trip insurance worth it?
If you travel more than twice a year, usually yes. One annual premium covers every trip within the year, up to a per-trip maximum (often 30–60 days), so from about three trips you are typically ahead of buying single-trip cover each time. Check that the maximum trip duration covers your longest planned journey.
What should I do if my claim is declined?
Use the insurer’s internal complaints process first, then escalate free of charge to the Insurance & Financial Services Ombudsman. Keep all documentation — receipts, police reports, medical notes — and remember that most claims must be lodged within 30–60 days of returning to New Zealand.
Related guides: House Insurance NZ, Life Insurance Explained for New Zealanders and Pet Insurance NZ.
No comments to show.
Best Brokers

Get approved fast with Finance Now. Personal loans, car finance & retail purchases – made easy for everyday Kiwis.

Shop now, pay later with Farmers Finance. Flexible payment options at Farmers stores across NZ – online and in-store.