Everything you need to know about the offset mortgage in New Zealand â how interest savings work, which NZ banks offer offset facilities, how to use an offset mortgage calculator, and how it compares to revolving credit.

Offset Mortgage NZ: How It Works, Which Banks Offer It and Whether It Suits You

An offset mortgage is one of the most powerful — and most underused — home-loan structures available in New Zealand. Instead of paying interest on your full loan, you pay it only on the difference between what you owe and what you hold in linked everyday and savings accounts. Done well, it can shave years off your loan and save tens of thousands of dollars, without locking away a single cent of your savings. This guide explains how offsets work here, which banks offer them, what they cost, and how to decide whether one suits you. It is general information, not financial advice.
Key points
- What it is: your linked savings are subtracted from your loan balance, so you pay interest only on the difference — calculated daily.
- Your money stays yours: savings remain fully accessible; an offset is not an extra repayment.
- Who offers it: only BNZ, Kiwibank and Westpac offer true offsets; ANZ and ASB use revolving credit instead.
- It is floating: offset rates (~6.3% in late 2026) are usually 1–2% above the cheapest fixed rates.
- Tax-free benefit: NZ taxes interest earned, not interest saved — so your offset effectively returns your mortgage rate, tax-free.
- Rule of thumb: worth considering once you consistently hold around $20,000+ (roughly 30% of the loan to offset a whole floating loan).
- Popular approach: split the loan — fix part for certainty, run part as a floating offset.
What an offset mortgage is and how it works
An offset mortgage links one or more of your transaction and savings accounts to your home loan. Rather than earning interest on those savings, the bank subtracts their combined balance from your loan balance and charges mortgage interest only on what is left. Your savings “offset” the debt — hence the name.
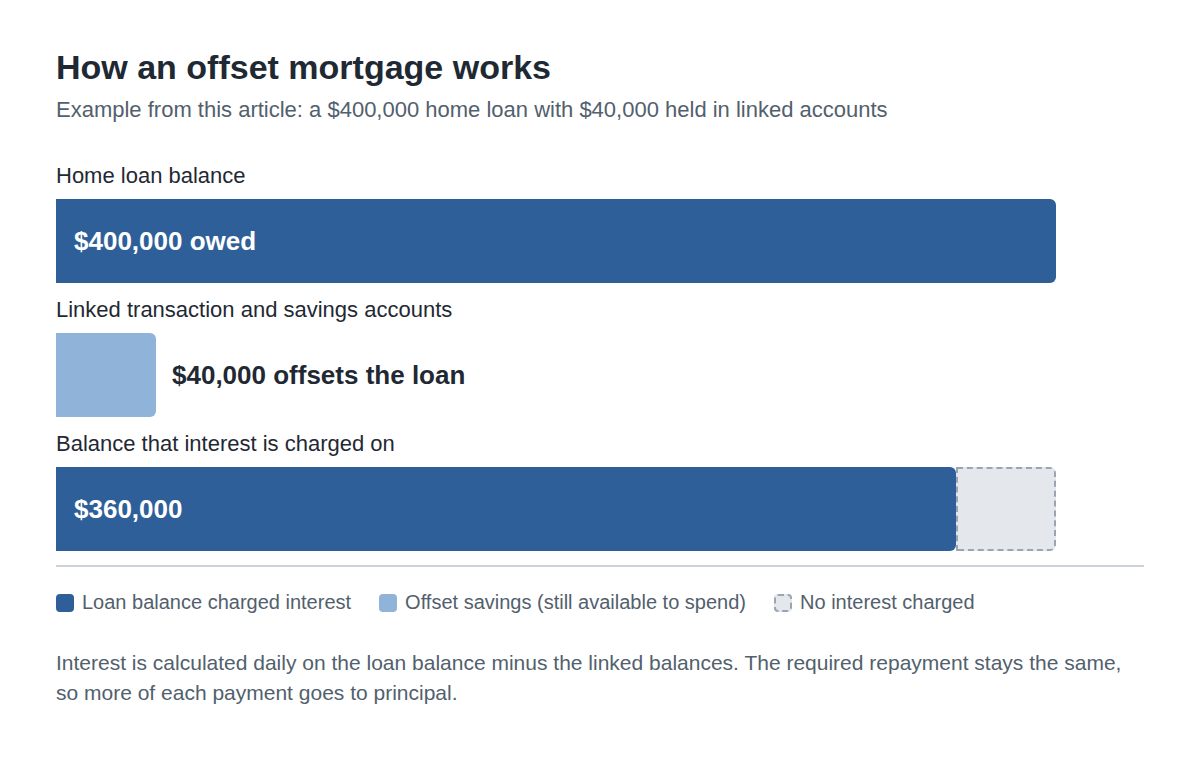
A simple example makes it clear. Say you owe $400,000 and hold $40,000 across your linked accounts. The bank charges interest as if your loan were only $360,000. You have not repaid anything and your money is still fully available to spend, but you are no longer paying interest on that $40,000.
Two features make this especially effective. First, interest is calculated daily, so even money that sits in the account briefly — your salary between pay cycles, GST you are holding for the taxman, a short-term cash buffer — counts for the days it is there. Second, your required repayment does not change. Because less of each payment now goes to interest, more goes to principal, so the loan falls faster and the term shortens on its own.
The practical takeaway: treat your linked offset account as your main transaction account. Have your pay deposited into it, keep your emergency fund there, and let every dollar work against your loan until you genuinely need it.
The tax advantage that makes offsets powerful
There is a quirk of New Zealand tax that turns an offset into one of the most efficient places to park cash. Interest you earn on a savings account or term deposit is taxable — your bank deducts resident withholding tax (RWT) at your marginal rate before you ever see it. Interest you save by reducing your mortgage balance is not income, so it is not taxed at all.
That means an offset effectively gives you a tax-free return equal to your mortgage rate. If your floating rate is 6.3%, every dollar sitting in your offset is “earning” a tax-free 6.3% by avoiding interest. To match that in a taxed savings account, a borrower on the 33% tax rate would need to find one paying roughly 9.4% before tax — which no mainstream savings account does. The higher your income, the more valuable this gap becomes.
Which New Zealand banks offer an offset mortgage
True offset mortgages are far less common in New Zealand than revolving credit, and only three of the main banks offer them: BNZ, Kiwibank and Westpac. ANZ and ASB do not offer a traditional offset — ANZ’s Flexible Home Loan and ASB’s Orbit are revolving-credit facilities instead (more on the difference below).
BNZ’s TotalMoney is the most feature-rich option. You can link up to 50 transaction and savings accounts, and its family-grouping feature lets parents offset their own savings against an adult child’s mortgage to cut the child’s interest — without transferring ownership of the money. BNZ charges a $10 monthly account fee (applied to one account in the group), plus any establishment costs.
Kiwibank’s Offset Home Loan lets you link up to eight everyday accounts — your own, plus a spouse or partner, parent, child or joint borrower (personal-name accounts only). Kiwibank does not charge a monthly offset fee, though a one-off establishment fee applies. Westpac’s Choices Floating with Offset lets you link a single offset account to the floating portion of a Choices home loan; it is single-account only rather than the multi-account approach the other two use.
For how these sit alongside the wider market, see our guide to how ANZ and BNZ mortgage rates are structured, and our overview of Westpac’s home-loan range. One caveat worth stressing: product availability, fees and account-linking rules change, so confirm the current offering directly with each bank before you decide.
Offset providers compared
| Provider | Product | Accounts you can link | Monthly fee | Family linking |
|---|---|---|---|---|
| BNZ | TotalMoney | Up to 50 transaction/savings accounts | $10/month (one account per group), plus establishment costs | Yes — partner, parents or children can link their savings |
| Kiwibank | Offset Home Loan | Up to 8 everyday accounts | No monthly offset fee; one-off establishment fee | Yes — spouse/partner, parent, child or joint borrower (personal names only) |
| Westpac | Choices Floating with Offset | Single linked offset account | Choices facility/package fees may apply | Limited — single offset account only |
All offsets are floating-rate only. Fees, account limits and linking rules change — confirm the current terms directly with each bank.
Offset vs revolving credit
Revolving credit is usually presented as the alternative to an offset, and both apply your savings against your loan — but they work differently, and the distinction matters.
A revolving-credit facility is essentially a large overdraft secured against your home. Your spending and your saving happen inside the loan account itself: your pay goes in (reducing the balance), and your spending comes straight back out (raising it). It is flexible and powerful, but it demands real discipline, because there is nothing structurally stopping the balance from creeping up.
An offset keeps your loan and your savings in separate accounts. The savings reduce the interest calculation mathematically, but they never mingle with the debt. For many people that separation is the whole point — it is much harder to accidentally spend your mortgage when it is not sitting in your transaction account. Both products are floating-rate. If you suspect you would treat a revolving facility as a spending account, the offset’s structural boundary is a genuine advantage; if you are highly disciplined, either can work.
Modelling your savings
Before committing, run the numbers. An offset calculator lets you enter your loan balance, your average linked-account balance (use a realistic daily average, not your peak), your floating rate and your remaining term. As an illustration, a $550,000 loan with $35,000 averaged across linked accounts, at a 6.3% floating rate, saves roughly $2,200 in the first year alone. Maintained over the life of the loan, that kind of balance can trim tens of thousands off the total interest bill and a couple of years off the term — without ever raising your required repayment.
You can model the numbers with Sorted’s free mortgage calculator, and check where floating rates currently sit on interest.co.nz. The key figure to watch is the gap between floating and fixed. In late 2026, floating rates sit around 6.25–6.4% while one-year fixed rates are closer to 5% — so the floating rate you pay on an offset is roughly 1–2% higher than the cheapest fixed rate on offer.
That premium is the hurdle the offset has to clear. You need enough in your linked accounts for the interest saving to beat the rate premium plus any fees. A rough rule of thumb is that an offset starts to pay for itself once your average offset balance is around 30% of your loan — or, put more simply, once you consistently hold $20,000 or more that you can keep accessible. But the maths is personal, and a split loan (below) lowers that threshold, so model your own numbers before deciding. For the wider rate picture, see our guide to NZ interest rates in 2026.
Is an offset right for you?
You are likely a good candidate if you consistently hold $20,000 or more in accessible accounts; you are comfortable with a floating rate; you have irregular income (freelancers, business owners and commission earners whose balance swings up and down benefit from the daily calculation); you value penalty-free access to your savings; you have family willing to link accounts; or you are a higher earner, which makes the tax-free saving worth more.
An offset may not suit you if you have modest savings and the rate premium would outweigh the saving; you strongly prefer the certainty of a fixed rate (offsets are floating, so repayments rise when the OCR rises — and the Reserve Bank lifted the Official Cash Rate to 2.75% in September 2026 and has signalled further gradual increases); you are a first-home buyer with little beyond your deposit; or you simply want the lowest headline rate, which fixed usually offers.
Many borrowers get the best of both with a split loan — fixing part for certainty and running part as a floating offset. For example, on a $550,000 loan you might fix $400,000 and run $150,000 as a floating offset, so you only pay the floating premium on the slice your savings can actually offset. A licensed mortgage adviser can help you find the right split, and you can read how structuring works alongside our home loans guide.
Fees and conditions to check
Offsets are not fee-free, and the fine print varies by lender. Before you sign, ask about:
- The monthly account fee for each eligible account type (BNZ’s TotalMoney carries a $10 monthly fee; Kiwibank’s Offset does not).
- Any establishment or legal fee to set the facility up.
- Which account types are eligible to link, and how many.
- The family-grouping rules, including what happens if a linked family member later wants their account removed.
- Any restrictions on lump-sum repayments or refinancing down the track.
And remember these are floating-rate products: when the OCR rises, your rate rises too, so budget for rate-rise scenarios rather than today’s figure. If your circumstances change, you can always look at whether it is worth switching — our guide on how to refinance your home loan covers the break fees and cashback clawbacks to watch. For independent, non-commercial comparisons of loan structures, Consumer NZ is a useful reference.
Tips to maximise the benefit
A few habits make a measurable difference to how much an offset actually saves you:
- Consolidate your cash. Move your emergency fund and other accessible savings into linked accounts so every dollar is offsetting.
- Bank your pay into the offset. Even if it leaves again within a fortnight, the daily calculation rewards every day it sits there.
- Use a credit card for day-to-day spending and pay it off in full each month from your offset, keeping more cash in the offset for longer (never carry a balance — card interest dwarfs any offset saving).
- Review fees annually. A monthly account fee can quietly erode the benefit if your average balance is low.
- Do not neglect KiwiSaver. Those funds cannot be linked to an offset, but keep contributing enough to capture the employer match and the government contribution (up to $260.72 a year) before you weigh whether extra voluntary contributions are better directed to your offset. Our guide to choosing a KiwiSaver fund explains the trade-offs.
Common mistakes to avoid
A handful of errors stop people getting the full value from an offset:
- Keeping savings in a separate, unlinked account. Money that is not linked does nothing for your loan — and if it is in a taxed savings account, you are earning a taxed return instead of saving a tax-free one.
- Paying the premium without the balance. Running the whole loan as a floating offset when you only hold a small cash buffer means you pay the floating premium on far more than your savings can offset. A split loan usually fixes this.
- Treating the offset as spending money. The saving only works if the balance stays genuinely high on average, not just on payday.
- Ignoring the fees. On a low average balance, a $10 monthly fee can swallow much of the benefit — do the sum for your own numbers.
Disclaimer
This article is general information about offset mortgages in New Zealand, not financial advice, and not a recommendation of any lender or product. Rates, fees, product availability and account-linking rules change and vary by lender — the figures here reflect 2026 and should be confirmed directly with each bank before you act. Offset mortgages are floating-rate products, so your repayments can rise if the Official Cash Rate rises. Consider advice from a licensed mortgage adviser for your own situation, and if you are struggling with repayments, free, independent help is available from MoneyTalks (0800 345 123).
Sources
- BNZ — TotalMoney offset home loan
- Kiwibank — Offset home loan
- Westpac NZ — home loan interest rates (Choices Floating with Offset)
- ASB — revolving credit vs offset (Orbit)
- Reserve Bank of New Zealand — the Official Cash Rate
- interest.co.nz — current mortgage rates
- Inland Revenue — resident withholding tax on interest
- Sorted (Retirement Commission) — mortgage calculator
- Consumer NZ — mortgages and choosing a loan structure
- MoneyHub NZ — offset mortgages explained
Frequently asked questions
How does an offset mortgage save me money?
You are charged interest only on your loan balance minus the money in your linked accounts, and the calculation is done daily. Because New Zealand does not tax the interest you save (only interest you earn), an offset gives you a tax-free return equal to your mortgage rate — which beats a taxed savings account, especially for higher earners.
Which New Zealand banks offer an offset mortgage?
Mainly three: BNZ (TotalMoney), Kiwibank (Offset Home Loan) and Westpac (Choices Floating with Offset). ANZ and ASB do not offer a traditional offset — they provide revolving-credit facilities (ANZ’s Flexible Home Loan and ASB’s Orbit) instead. Availability changes, so confirm with each bank.
Is an offset better than a fixed-rate mortgage?
It depends on how much you hold in savings. Offset rates are floating and currently sit around 1–2% above the cheapest fixed rates, so you need enough offset balance for the saving to beat that premium — a rough guide is around 30% of your loan. Below that, a cheaper fixed rate may win, which is why many borrowers split their loan.
Do I lose access to my savings in an offset?
No. The money stays fully accessible for spending and emergencies. You are not making an extra repayment — you are simply reducing the balance interest is charged on. Your regular repayment stays the same, but more of it goes to principal.
Can family members link their accounts to my offset?
Yes, with some banks. BNZ’s TotalMoney allows up to 50 accounts including family members’, and Kiwibank’s Offset allows up to eight including a spouse or partner, parent or child (personal-name accounts only). Each account holder keeps full access to their own money; they simply forgo the interest they would have earned on it.
No comments to show.
Best Brokers

Get approved fast with Finance Now. Personal loans, car finance & retail purchases – made easy for everyday Kiwis.

Shop now, pay later with Farmers Finance. Flexible payment options at Farmers stores across NZ – online and in-store.